The structural tailwinds that powered private equity’s golden age have faded. Ahead of SuperReturn Europe, Imogen Richards, Partner and Head of European Primaries at Pantheon, examines why operational value creation and deep specialism matter more in today’s uncertain environment and what the performance data reveals about specialist managers.
Key takeaways
- The old tailwinds have faded: Cheap leverage, expanding multiples, globalisation and relatively calm markets created unusually supportive conditions during the 2010s.
- Specialists have led in the data: Across the 2010–2022 vintages, specialist buyout funds generated higher pooled IRRs and lower loss rates than their generalist peers.
- Operational improvement matters more: Specialist managers generated a greater share of equity value through EBITDA margin expansion and relied less heavily on multiple expansion.
- Expertise can improve access: A strong sector reputation may help managers source, secure and add value to investments.
When private equity had a structural tailwind
It may be that every investor reaches the point in their career where they believe everything was easier in the good old days: deals were simpler to find, there was less competition for transactions and returns flowed more easily.
But for many of us working in private equity, our recollection of a “golden age” in the 2010s is backed by solid macroeconomic data.
In the decade from 2010 to 2020, several supportive structural tailwinds converged to create attractive conditions for our asset class.
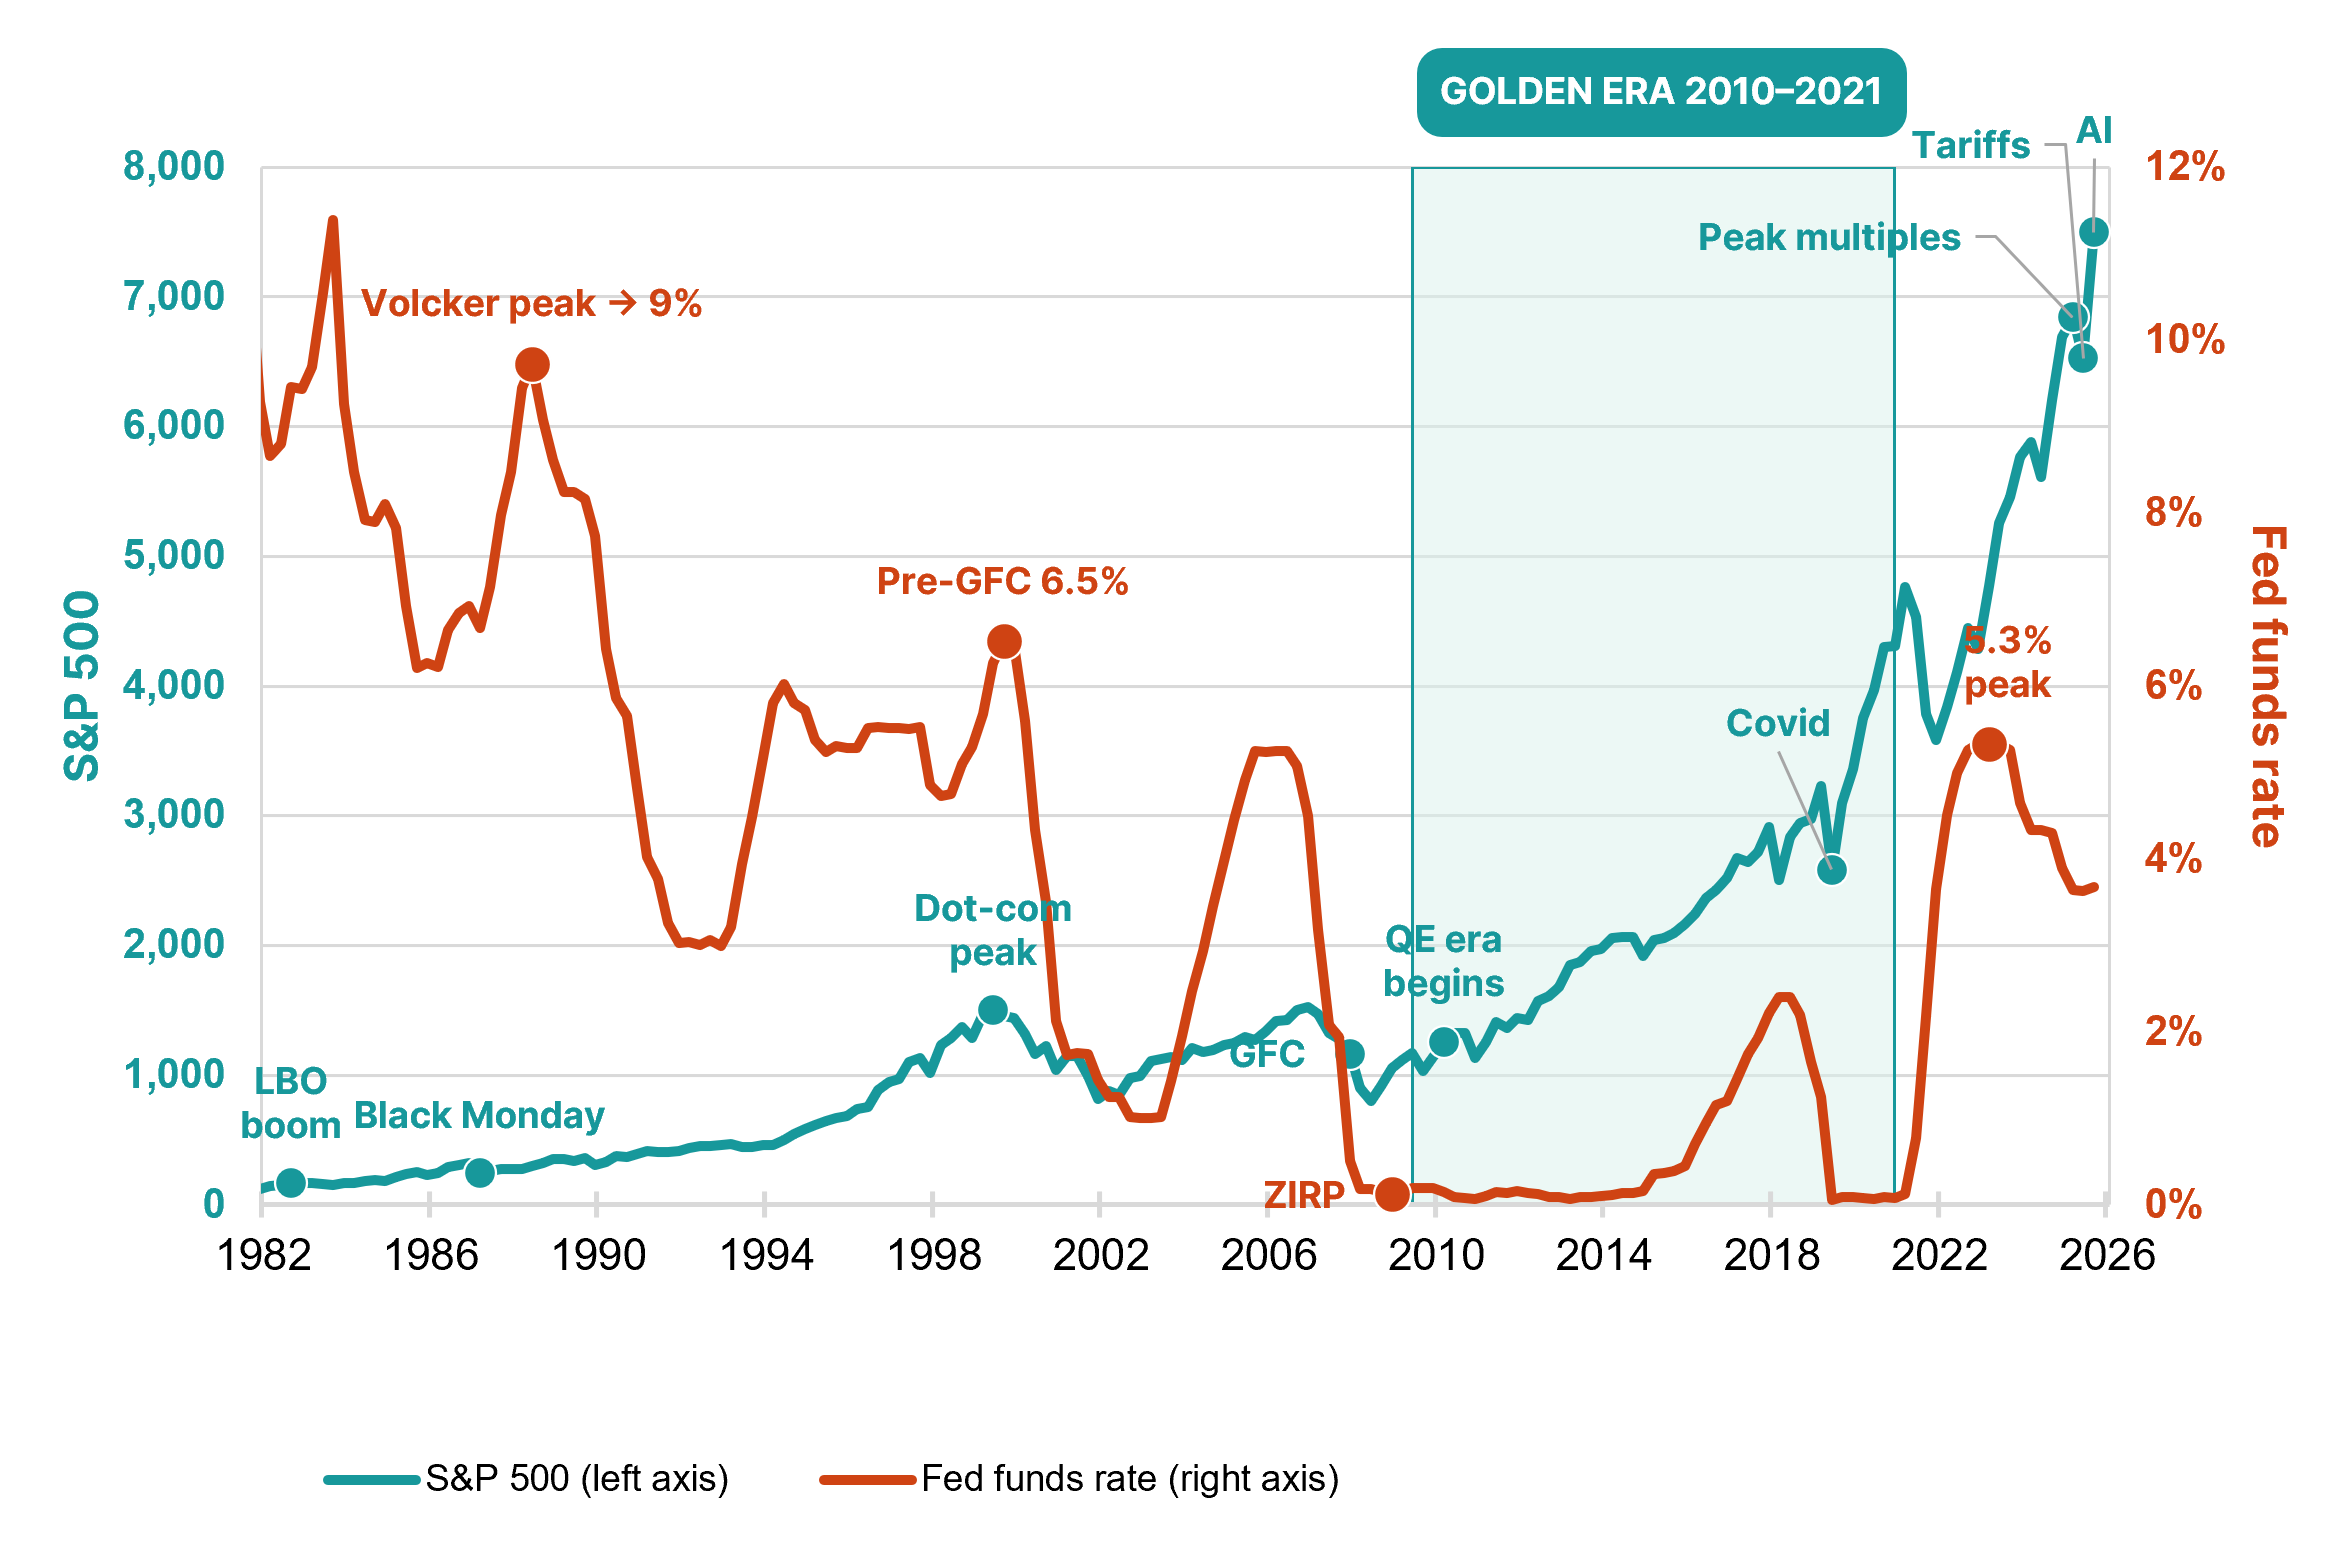 Structural tailwinds converged in the 2010s to create an unparalleled environment for PE returns
Source: LSEG, Federal Reserve Bank of St. Louis as of September 2026. Labelling of eras is Pantheon opinion. For illustrative purposes only.
Rates were at historic lows, cheap leverage was available and the IPO window was wide open as the S&P 500 tripled between 2013 and 2021. Entry multiples expanded from around 9x EBITDA in 2013 to more than 12x by 2021. It was this expansion in multiples, rather than operational improvement, that drove a meaningful share of buyout value creation over the decade.
The period also coincided with several years of relative geopolitical calm and strong globalisation. Portfolio companies were able to benefit from frictionless trade and labour-cost arbitrage, while private equity funds generated strong returns.
Between 2012 and 2019, top-quartile funds averaged IRRs of around 20%. This “golden age” was the culmination of four decades of compounding macroeconomic tailwinds. Those structural supports are now almost all gone, and today’s GPs are operating without the same helpful backdrop.
This ‘golden age’ was the culmination of four decades of compounding macroeconomic tailwinds. Those structural supports are now almost all gone
Imogen Richards, Partner, Head of European Primaries, Pantheon
The times are a-Changin
Today’s investment environment is marked by greater volatility and uncertainty. There is also more competition for deals, debt is more expensive and growth is harder to find.
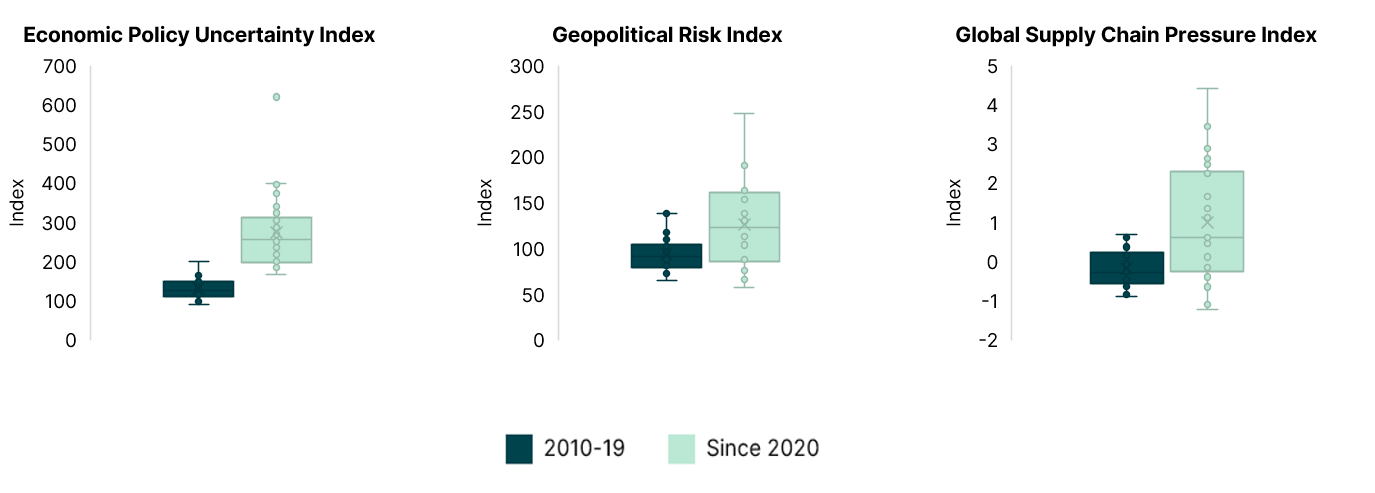 Note: Box-and-whisker plots are constructed on quarterly data for all variables.
Sources: Geopolitical Risk Index from Caldara, Dario and Matteo Iacoviello (2022), “Measuring Geopolitical Risk,” as of September 2026; Economic Policy Uncertainty Index from Davis, Steven J., 2016. “An Index of Global Economic Policy Uncertainty,” as of October 2026.; Global Supply Chain Pressure Index from Federal Reserve Bank of New York as of October 2026.
When underwriting private equity investments, GPs must consider a wide range of potential outcomes. When the backdrop is more uncertain, that range becomes wider and there is less certainty around outcomes. There may therefore be less willingness to commit new capital without confidence in the downside protection.
In this new environment, hold-period assumptions must account for a much wider range of potential policy outcomes. Fluctuating interest rates mean GPs cannot assume that the cost of debt at entry will approximate the cost of debt at exit.
Timing exits is also harder, while the public-market comparables used to anchor private valuations are themselves more volatile. For portfolio companies with physical supply chains, shifting tariffs can create margin volatility that is genuinely difficult to hedge, while making capital-expenditure decisions more challenging.
Why specialism matters now
This is not to say there is no longer an opportunity to generate strong returns from private equity, but a different playbook is needed.
The flat or declining multiples and higher financing costs seen today are likely to create greater dispersion between private equity managers. Because the landscape is more uncertain, liquidity around assets with more nuanced stories is also likely to be more challenged.
That places greater emphasis on operational value creation. Managers with deep specialisms, whether in particular subsectors, geographies or value-creation capabilities, are increasingly differentiating themselves from generalist peers through stronger performance and more resilient value creation.
Across the 2010–2022 vintages, specialist buyout funds generated better returns than their generalist peers. According to McKinsey research, specialists delivered higher pooled IRRs than generalists, at 17% versus 13%; more attractive total-value multiples, at 2.2x versus 2.1x; and lower loss rates, at 9% versus 12%.
The stronger performance of specialists is underpinned by a distinct focus on operational value creation.
Compared with generalist buyout funds across the 2010–2022 vintages, specialists generated nearly four times as much equity value through EBITDA margin expansion, 43% versus 10%, while delivering a similarly high share of value through revenue growth, at 86% versus 82%.
Notably, specialists’ returns were also largely independent of multiple expansion (5% versus 35% for generalists), highlighting a more resilient and less market-dependent return profile.
Imogen Richards, Partner, Head of European Primaries, Pantheon
Specialism can help managers win deals
None of this is to suggest that generalist buyout managers are inherently weaker. Many of the firms regarded as generalists are highly proven and capable GPs with specialisms in areas such as complex transactions or value creation.
However, generalists focus on a broader opportunity set than their specialist peers and may therefore be disadvantaged when sourcing and diligencing opportunities, and ultimately, when securing deals.
We hear repeatedly from our GPs that their reputation as a specialist in a particular industry went a long way towards winning over the management team of a company they were trying to acquire, whether through a proprietary, bilateral or competitive process.
Specialism is not only an advantage when securing an opportunity. It can also help managers add value following an acquisition. Specialist GPs with proven value-creation expertise can drive real alpha generation.
This is clearly a key consideration for investors pursuing primary or co-investment strategies. For secondaries investors, maintaining relationships with a network of specialist GPs with extensive experience of accessing difficult-to-reach assets is equally important.
Where the opportunity now lies
Those of us who remember the golden age are right that conditions were easier a decade and a half ago. But an easier backdrop rewarded everyone.
Today’s environment rewards the specialist, and that is where the opportunity now lies.
An easier backdrop rewarded everyone. Today’s environment rewards the specialist.
Imogen Richards, Partner, Head of European Primaries, Pantheon
Sources
S&P Dow Jones Indices: S&P 500. Index levels cited: 1,426.19 on 31 December 2012 and 4,766.18 on 31 December 2021.
Bain & Company, Global Private Equity Report 2022, drawing on CEPRES data.
McKinsey & Company, Global Private Markets Report 2026: Private equity. Figures cited relate to 2010–22 vintage buyout funds.
Chart 1 sources: LSEG Data & Analytics and Federal Reserve Economic Data, Federal Reserve Bank of St. Louis, as of September 2026. Labelling of eras is Pantheon opinion. For illustrative purposes only.
Chart 2 sources: Caldara and Iacoviello, “Measuring Geopolitical Risk” (2022), as of September 2026; Davis, “An Index of Global Economic Policy Uncertainty” (2016), as of October 2026; and the Federal Reserve Bank of New York’s Global Supply Chain Pressure Index, as of October 2026.
Statements identified as such in the article represent Pantheon opinion.