We wrote at Europe's FX Open that there have been no huge changes, but the USD is softer across the board as BBC News reports the Democrats win the Senate and the House, taking control of Congress for the rest of the Trump presidency.
It is being viewed as a historic rout of the Republican Party. In the Senate race, Democrats picked up a string of surprise victories in Republican strongholds, including Texas, Ohio, and Kansas - which last elected a Democrat almost 100 years ago.
Trump told Fox News that the Democrats "did a good job", adding: "I'm a little surprised." He also told the NYT that he would accept the election results and was prepared to work with Democrats. The latter in particular could well be reassuring markets and to dampen moves so far, as there was a fear beforehand that Trump could challenge results that were to go against him.
It will be interesting to see how far traders, investors look to push the USD lower from here. The YEN and CHF have both made light haven related gains so far, but moves have been orderly.
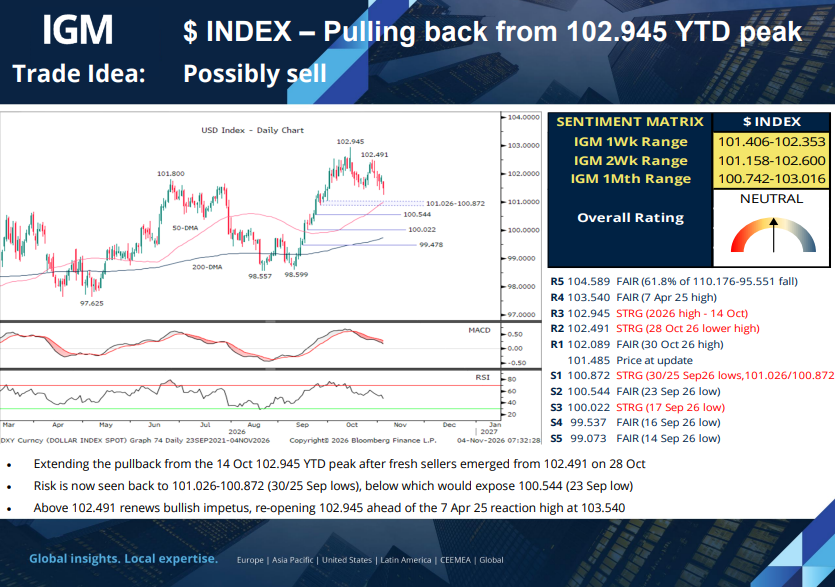
So far, the DXY USD Index has fallen to a new five week low of 101.25 albeit still relatively frothy levels. Next downside targets look to be 100.75, 100.20-25, the psychological 100.00 mark and the arguable near-to-medium term pivot at 99.73 and the 200-dma. The DXY has held north of the latter unbroken since mid-September.
The aftermath
There are worries. The results could lead to gridlock on the debt ceiling, a prolonged 2027 government shutdown and could encourage Trump to pursue an even more activist foreign policy agenda.
Yes, these possibilities are speculative, arguably worse case scenarios and much will depend on Trump after.
Other drivers
Fundamentals and yield differentials arguably still lend support to the USD.
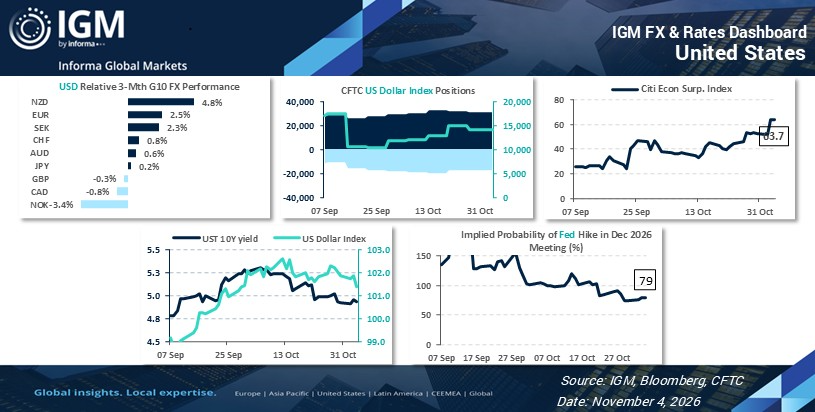
Fed rate hike expectations remain relatively frothy and a USD prop. See Dashboard. Implied probability of a Fed rate hike by December stands at 79% and higher on the week so far.
And, of course, much will depend on G10 counterparts, as the EUR continues to look relatively unattractive still on all things France. GBP is currently buoyed by some UK economic resilience; the CHF and YEN are enjoying some haven related support and the AUD should still attract carry king demand even after the latest perceived less than hawkish RBA hike.
Other firms views
We will publish the views of some other leading firms through the course of the European session.
IGM tech view