So much for the weight of Friday's collection of NFPs misses (29k and revised softer 233k last, 4.3% and 0.1% m/m and 3.0% y/y) working to cast increased doubt on October Fed rate hike chances and leading to a genuine USD pullback, correction even.
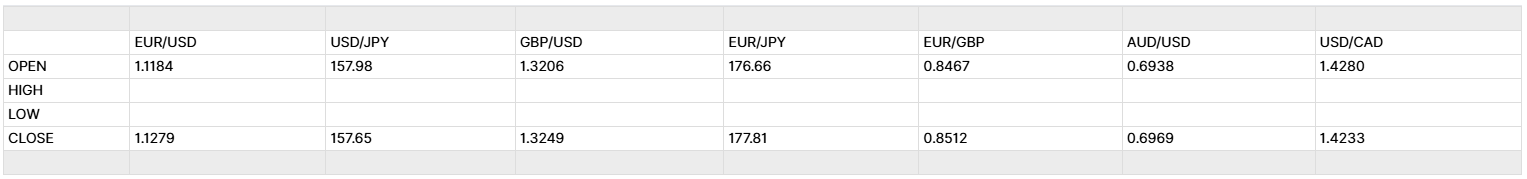
The DXY USD Index has made semi-spike fresh 2026 highs of 102.54 today (vs Thursday's 102.21 previous peak), as EUR/USD plumbs new depths below 1.1200 and endures broad, independent losses.
We warned on contagion issues Friday and Spain's left wing government is said to be readying for an early election after last week's big loss in parliament. And, Yardeni Research warned France may be on the verge of a full-blown debt crisis and is the euro area’s weakest economic link.
So, the bond market will be under an intense spotlight today, but it's also busy schedule wise.
Services and composite PMIs results will be a focus in Europe through the morning. We also get Eurozone PPI for August and a likely jump in producer prices.
Standout release looks to be the US ISM services index, with a 55.0 forecast in Sep vs 55.4 last. Post-payrolls, we stay data dependent to an extent and there are some notable US releases this week though there is a feeling that next key report is CPI on the 14th.
There is a host of ECB speak scheduled too.
On the news front, Director of the US National Economic Council Kevin Hassett called on former Fed Chair Jerome Powell to leave the central bank’s board. “I think that it’s time for him to move on,” he said on Fox News.
Bbg reports Japan’s parliament opened today with bills aimed at easing the impact of inflation on households set to dominate the agenda, as PM Takaichi seeks to put her grand plans for Japan’s economy and finances into action.
And, The Times reports the UK is preparing to impose import levies on Chinese electric vehicles to meet a key demand from the EU in a blow to a group that now accounts for nearly one in four cars sold in the country.