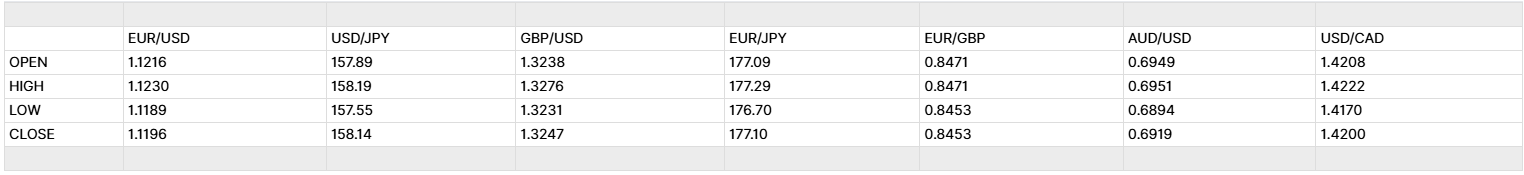
The DOLLAR traded in a sideways manner for most of the session, but ends today's trade down slightly, as markets concentrated more on equity and bond market developments.
An underwhelming revenue update from Anthropic and concerns over the future of cloud provider CoreWeave has once again seen the market call into question whether lofty AI valuations are justified. The rotation out of equities and into safe haven government debt helped US 10 year yields fall back below 5.04% at one stage, its lowest level in three weeks.
The Aussie was a major FX underperformer, with selling spilling over from the Asian session, after the dismal Australian employment report for September. Having traded up at 0.7013 before yesterday's US CPI print, Aud/Usd slumped to 0.6894 in afternoon trade.
A much faster than expected US PPI only added to US inflation concerns. The headline PPI reading for September accelerated to 6.3% y/y, from an upwardly revised 5.6% y/y print in August, which is the highest reading since December 2022. Ex food and energy, the reading rose to 5% y/y from another upwardly revised 4.8% y/y in August, again significantly above the 4.4% y/y forecast.
After the US CPI and PPI prints for September, Samuel Tombs at Pantheon Macro is estimating we will see a 0.36% m/m rise in the core PCE deflator. Tombs thinks that this means October's FOMC meeting probably still results in a hold decision, but a December rate hike now looks very likely.
Looking back at the headline PPI rise of 1.3% m/m, it was significantly above the estimate for 0.6% and was the highest reading since March 2022, which was the first full month of the Russia-Ukraine war. Liz Thomas at SoFi points out that it wasn't just oil, without Energy's contribution, the m/m rate would have still been over 0.6%.
The US retail sales numbers were above consensus on a headline and ex autos basis, but the GDP feeding control group figure was a disappointment. Retail sales ex autos rose by 0.9% m/m vs the 0.5% forecast, but the control group figure only rise by 0.1%, which was underneath the 0.3% expected.
Meanwhile, the Empire Manufacturing survey for October rose to 25.5 from 7.6, but the Philly Fed survey also for October fell to 20.9 from 37.8. Finally jobless claims rose to 199k from 198k the week previous.
Earlier, UK GDP surprised to the upside once again, with growth rising by 0.1% in August compared to the fall of 0.1% that was expected. Sterling also benefited from comments by UK Chancellor Healey who declared that the government will meet the fiscal rules.